Financial expansion: Banking access points grow by 44% in the Dominican Republic
The Dominican financial system has undergone a significant transformation in its physical infrastructure. According to data from the Association of Multiple Banks of the Dominican Republic (ABA), banking access points recorded a 44% increase over the last eight years, rising from 4,704 units in 2015 to 6,777 at the close of 2023.
This growth responds to a decentralization and modernization strategy, where ATMs and banking sub-agents have played a leading role in bringing services closer to sectors traditionally excluded from conventional banking.
X-ray of service channels
At the end of 2023, the in-person service network was consolidated through 885 branches, 3,322 ATMs, and 2,570 banking sub-agent points. The report highlights how each channel fulfills a specific role within the financial ecosystem:
- Branches: They maintain their relevance for complex transactions, loans, and personalized service, despite a slight 4.5% reduction in their total number since 2015.
- ATMs: They are consolidated as the main physical channel, facilitating withdrawals, deposits, and inquiries, with a network that continues to expand nationwide.
- Banking sub-agents: They represent the key piece in financial inclusion, transforming local businesses into service counters and allowing access to remote communities.
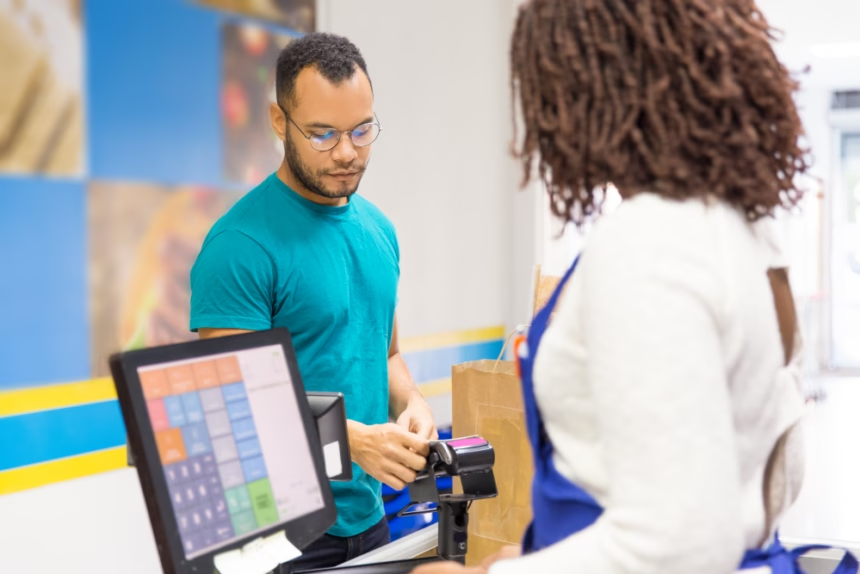
Banking sub-agents become an extension of the bank with businesses operating as teller windows, reaching communities far from branches.
Association of Multiple Banks of the Dominican Republic (ABA)
Decentralization towards the South and the East
One of the most relevant findings of the analysis is the geographical distribution of sub-agents. While in 2015 the Metropolitan Zone and the North concentrated the vast majority of these points, by June 2026 a notable change has been observed: the South region increased its share to 23.01% and the East region to 14.21%.
This trend demonstrates that banking is prioritizing coverage in areas where access to financial services was historically limited. The operational flexibility of sub-agents, compared to the high maintenance cost of a traditional branch, facilitates this dynamic expansion.
The future of financial access
The ABA emphasizes that, although digitalization is advancing by leaps and bounds, allowing for 24/7 operations, physical banking remains indispensable for a large part of the population. The future of these channels will depend on the sector’s ability to integrate technology with an efficient physical presence, achieving a balance between digital modernization and the need for direct service in the most vulnerable communities.